South Melbourne, VIC
South Melbourne Business Debt and Finance Broking
Agencies above the market, trades behind it, and a hospitality strip that never quite stops. WeL’nd is one suburb away, working with South Melbourne owners on tax and trading debt.
Studios, suites and a market that anchors it all
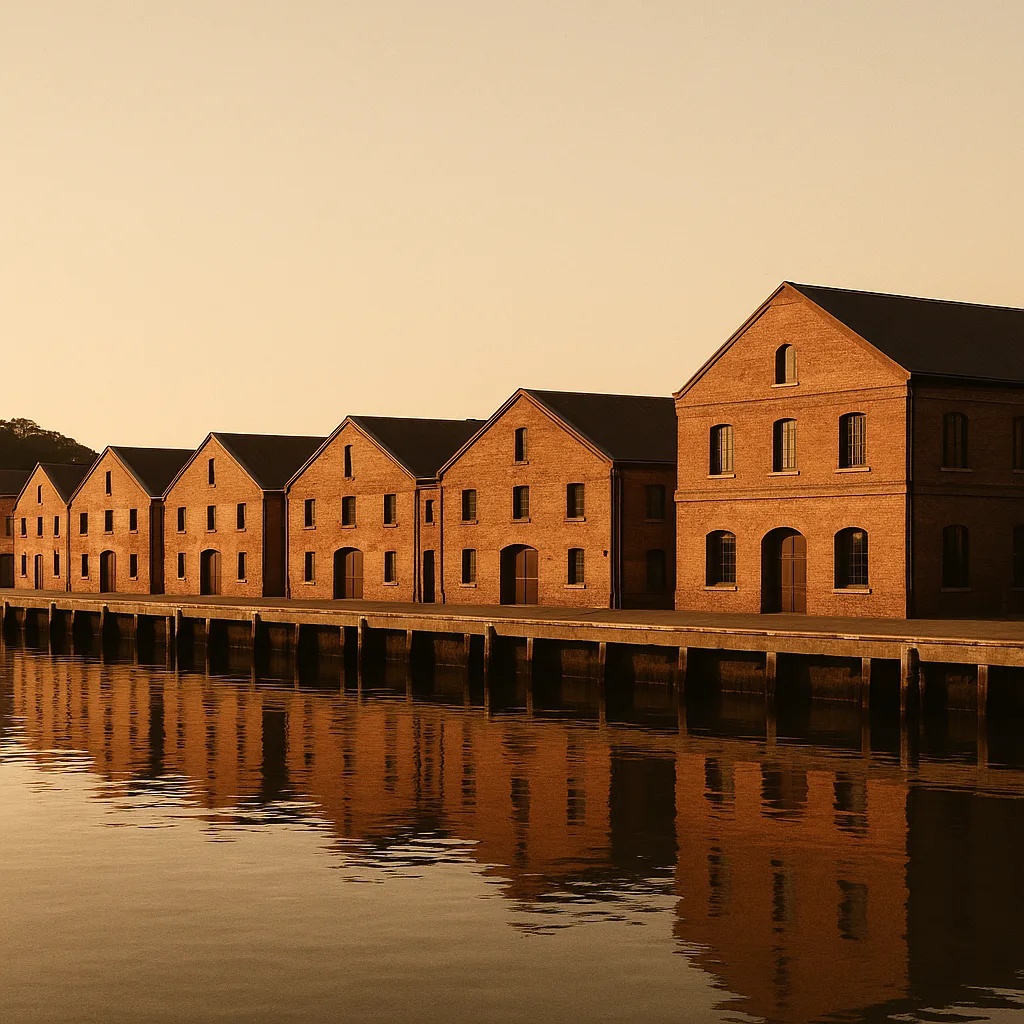
South Melbourne's business base is one of the densest small-business clusters in inner Melbourne. Converted warehouses along Cecil, Coventry and the side streets hold design studios, agencies, architects, technology firms and professional suites. The market and Clarendon Street carry food retail, hospitality and specialist traders, many of them family run over decades. Behind that sits a persistent layer of trades and light service businesses.
It is an expensive place to occupy. Rents are high, fit-outs are expensive, and lease guarantees are usually personal. That combination shapes almost every debt conversation we have in the postcode.
The market itself anchors a food and grocery trade that has been operating in the same streets for generations, some of it now run by the third generation of the same family. Those businesses tend to be conservatively financed and stubbornly private about pressure, which means they often arrive later than they should. Earlier is always cheaper.
Where the debt usually comes from here
- Fit-out and equipment costs funded from working capital instead of a facility
- Project-based fee income that arrives in lumps while wages go out fortnightly
- A personally guaranteed commercial lease that has become the largest fixed cost in the business
- GST collected and used, then a BAS lodged and not paid, then another
- Short-term unsecured lending taken to bridge a gap and rolled more than once
For hospitality and retail operators the pattern is sharper still, because the trading day is long, the margins are thin, and the tax account is the only creditor that does not ring on the day it is due. By the time it does ring, the general interest charge has been compounding for a while.
There is also a timing problem particular to agencies and studios. Fees are billed on milestones, staff are paid fortnightly, and a single client deferring a project moves a quarter. Where the underlying business is sound, that is a working capital gap rather than a solvency problem, and it deserves a facility rather than the tax account.
Equity in the postcode, and what lenders make of it
South Melbourne housing runs from Victorian terraces and workers' cottages through to warehouse conversions and newer apartment buildings. The period stock is well understood by lenders and long-held homes here have frequently accumulated substantial equity. Newer apartments, especially smaller floor plans, sit under policy restrictions at several lenders. Warehouse conversions can attract closer valuation attention where the floor plan is unusual or the zoning is mixed.
Where a business owns its premises, that commercial security is often the better route, because it keeps the home out of the structure. It depends on the equity and on the lender's view of the property.
Where a business occupies premises on a long lease with a make-good obligation at the end of it, that obligation is a real liability even though it does not appear on most debt lists. Raise it early, because lenders take it into account and owners routinely forget it exists.
Ten minutes from our office
WeL’nd is at 1/3 Westside Avenue, Port Melbourne, a short drive from Clarendon Street. Local clients often come in. Just as many do everything by video and secure upload because it is faster and their accountant can join. The process does not change either way.
Before the first call, gather a list of every debt with payout figures rather than balances, plus your current lease terms and any personal guarantee you have given. Those three things shape most of what follows.
Our office
We are based in Port Melbourne and work across Australia.
Most of what we do happens by phone, email and video, wherever you are. If you are close by and would rather sit down, the door is at 1/3 Westside Avenue, Port Melbourne.
FAQ
Questions from South Melbourne
If yours is not here, ask it. We would rather answer the awkward one early than have you find out later.
1300 015 26701How close is WeL’nd to South Melbourne?
+
02I have personally guaranteed my lease. Does that affect borrowing?
+
03Can fit-out costs be refinanced?
+
04My income is project based and irregular. Is that a problem?
+
05Can I keep my home out of it?
+
06Does WeL’nd negotiate with the ATO?
+
Credentials
- Credit Representative 554029
- ABN 20 672 801 651
- FBAA member
- AFCA external dispute resolution
Nearby
Other areas we work
Port Melbourne, VIC
WeL’nd is based at 1/3 Westside Avenue, Port Melbourne.
Read moreSouthbank, VIC
Southbank apartment owners and hospitality operators refinancing, consolidating debt or dealing with ATO arrears.
Read moreMelbourne, VIC
A Port Melbourne brokerage for business owners carrying ATO and unsecured debt.
Read moreSt Kilda, VIC
St Kilda hospitality operators, sole traders and homeowners facing ATO arrears or unsecured debt.
Read moreRichmond, VIC
Richmond business owners with ATO arrears, fit-out and equipment finance or unsecured debt.
Read moreVictoria
Victorian business owners carrying ATO and unsecured debt.
Read more
Talk to someone who has seen worse.
Tell us the honest position and we will tell you early whether we can help. No judgement, and no fine-print games.
Or call us
1300 015 267Monday – Friday, 09:00 to 17:30
Head Broker
Speak to Dave Pham